Loan management software for small lenders: 6 things to check before you pick one
Last updated
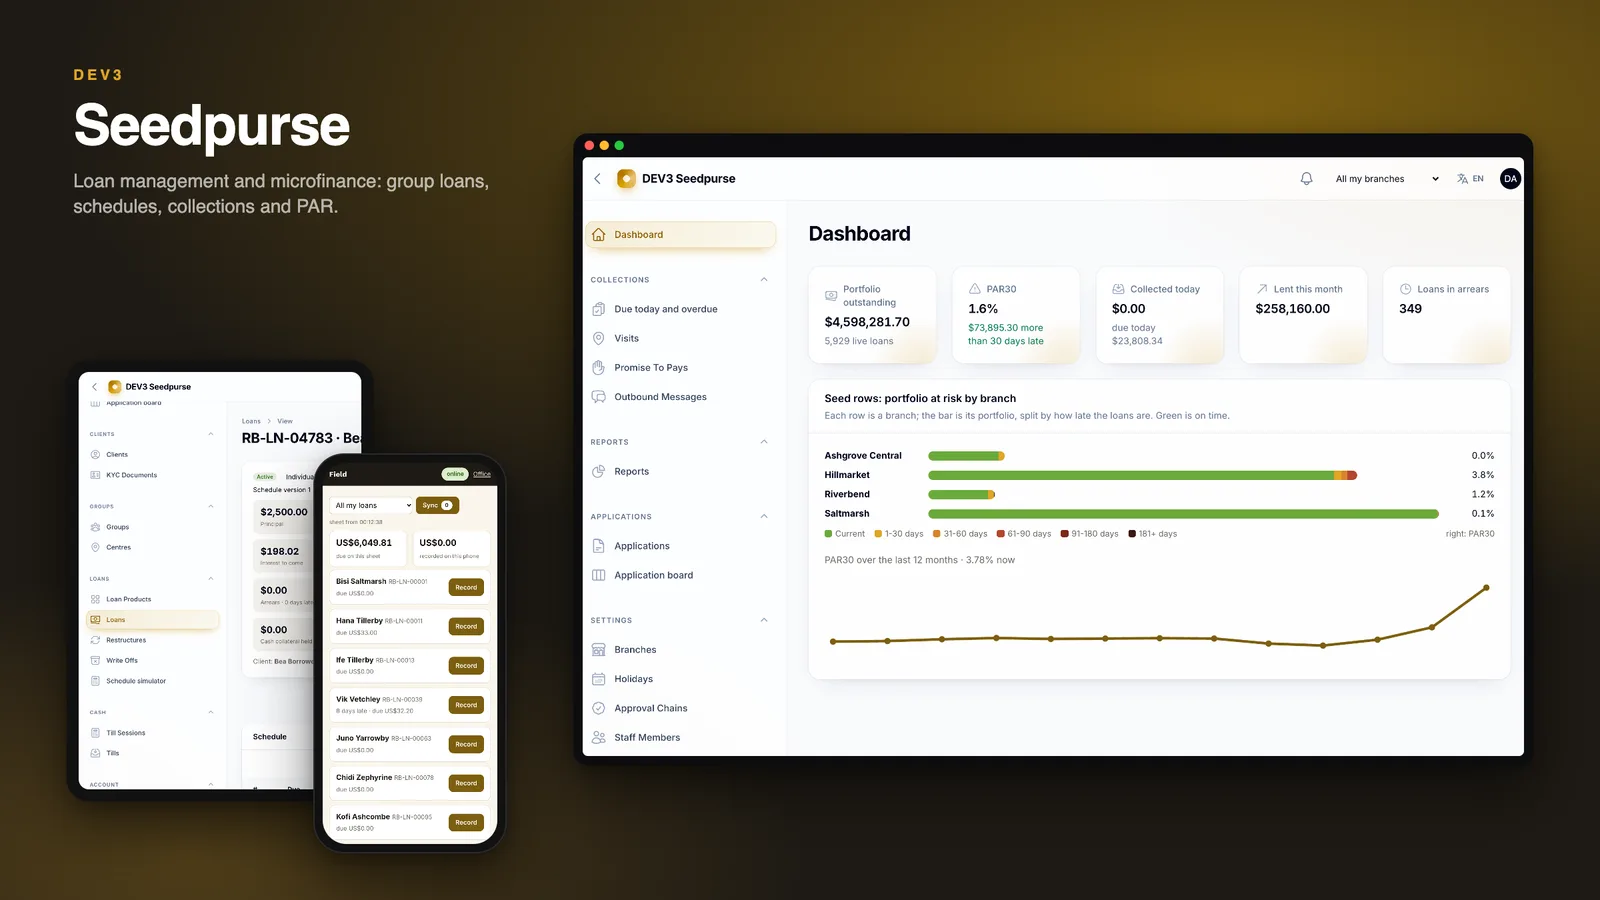
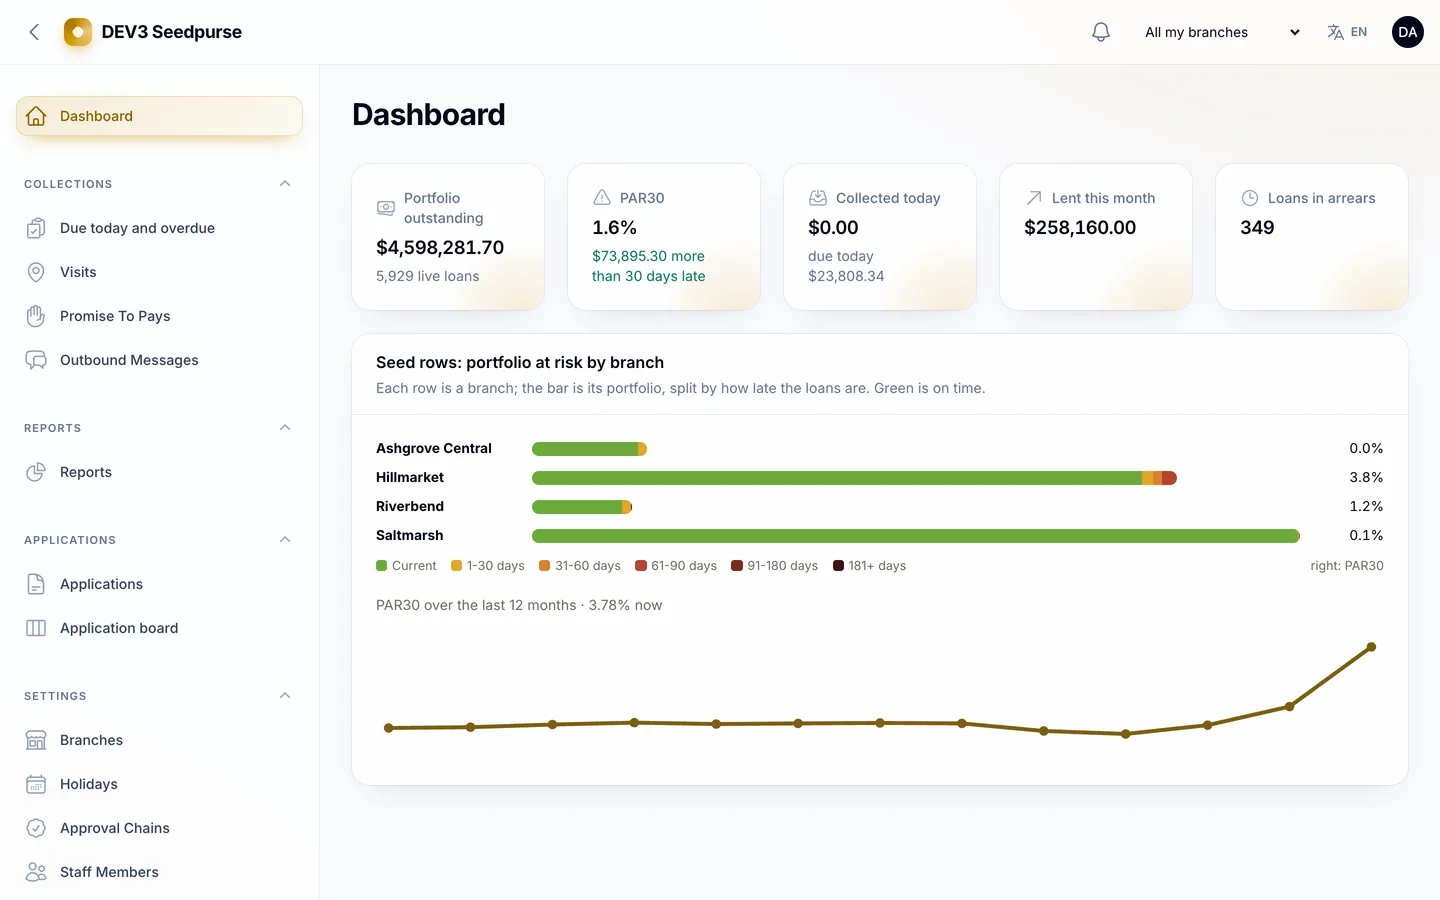
Lending software is easy to demo and hard to get right. Here are six things to check before you pick a loan management system, with DEV3 Seedpurse as the worked example.
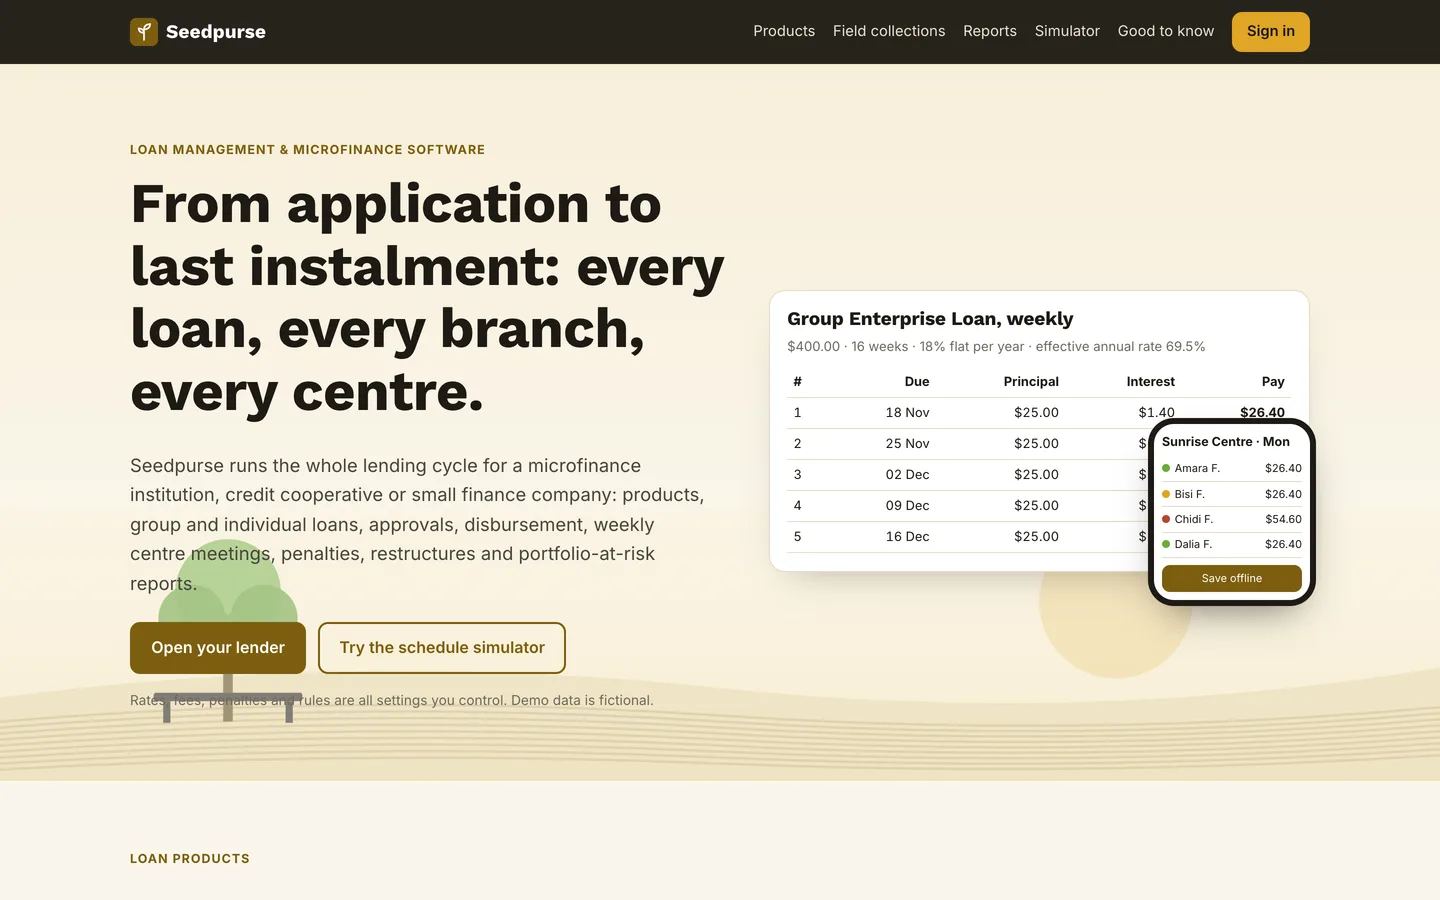
1. Can you configure the products you actually offer?
Flat, declining balance, equal principal and interest-only with a balloon are different products with different maths. Check that fees, grace periods, penalties and caps are settings, and that you can see every instalment and the effective rate before a loan exists. Seedpurse has a product builder and a schedule simulator for exactly this. Rates and rules are yours to set and to check against the rules that apply to you.
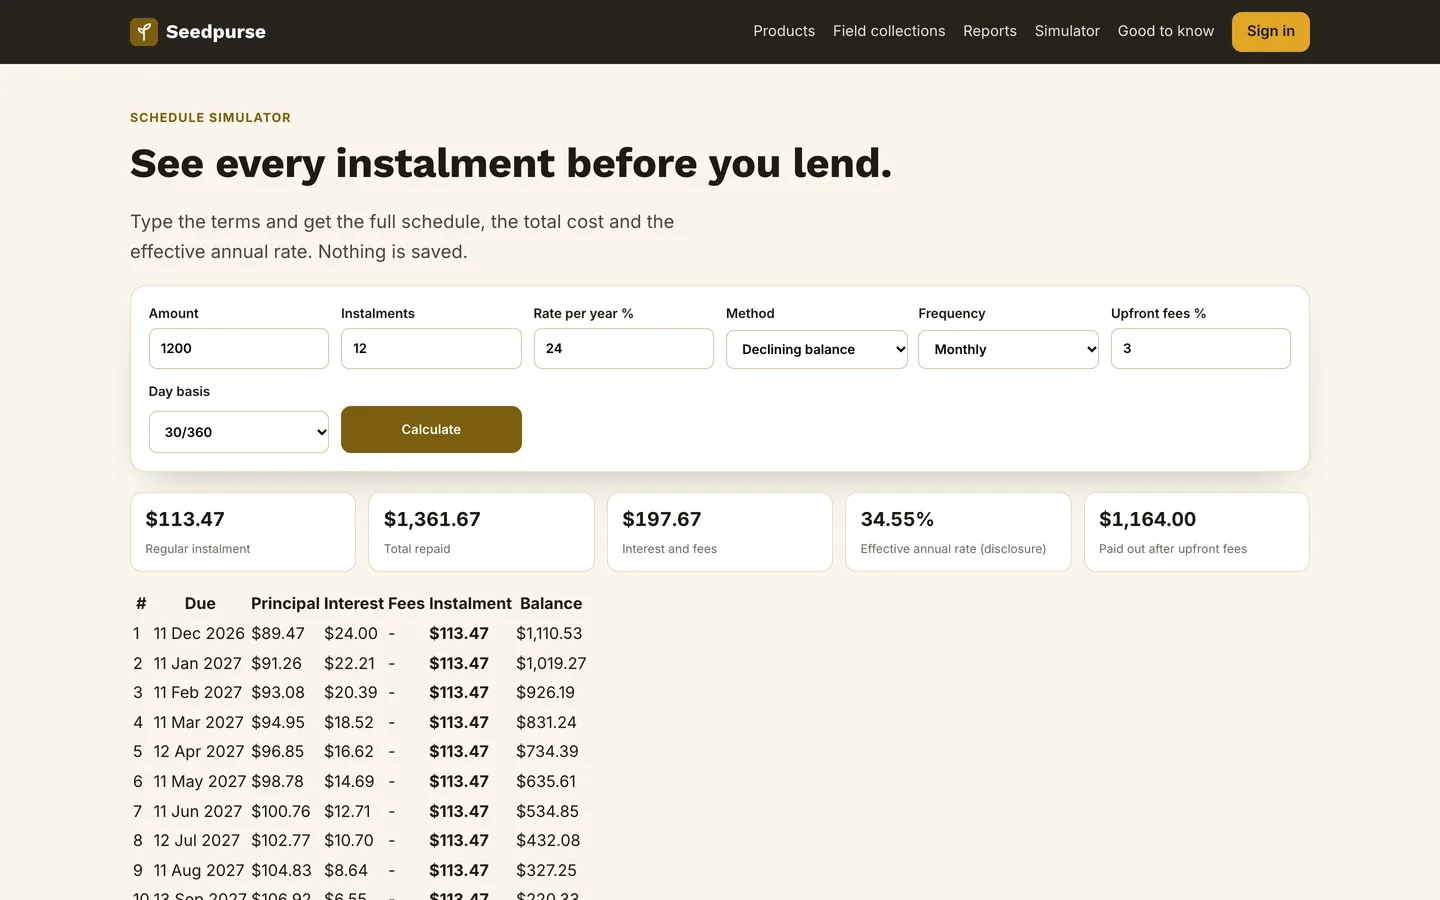
2. Does it handle groups, KYC and approvals?
Group lending needs joint liability, guarantors and documents checked by a second person. Approvals should follow amount bands, with n-of-m signatures and nobody approving their own work.
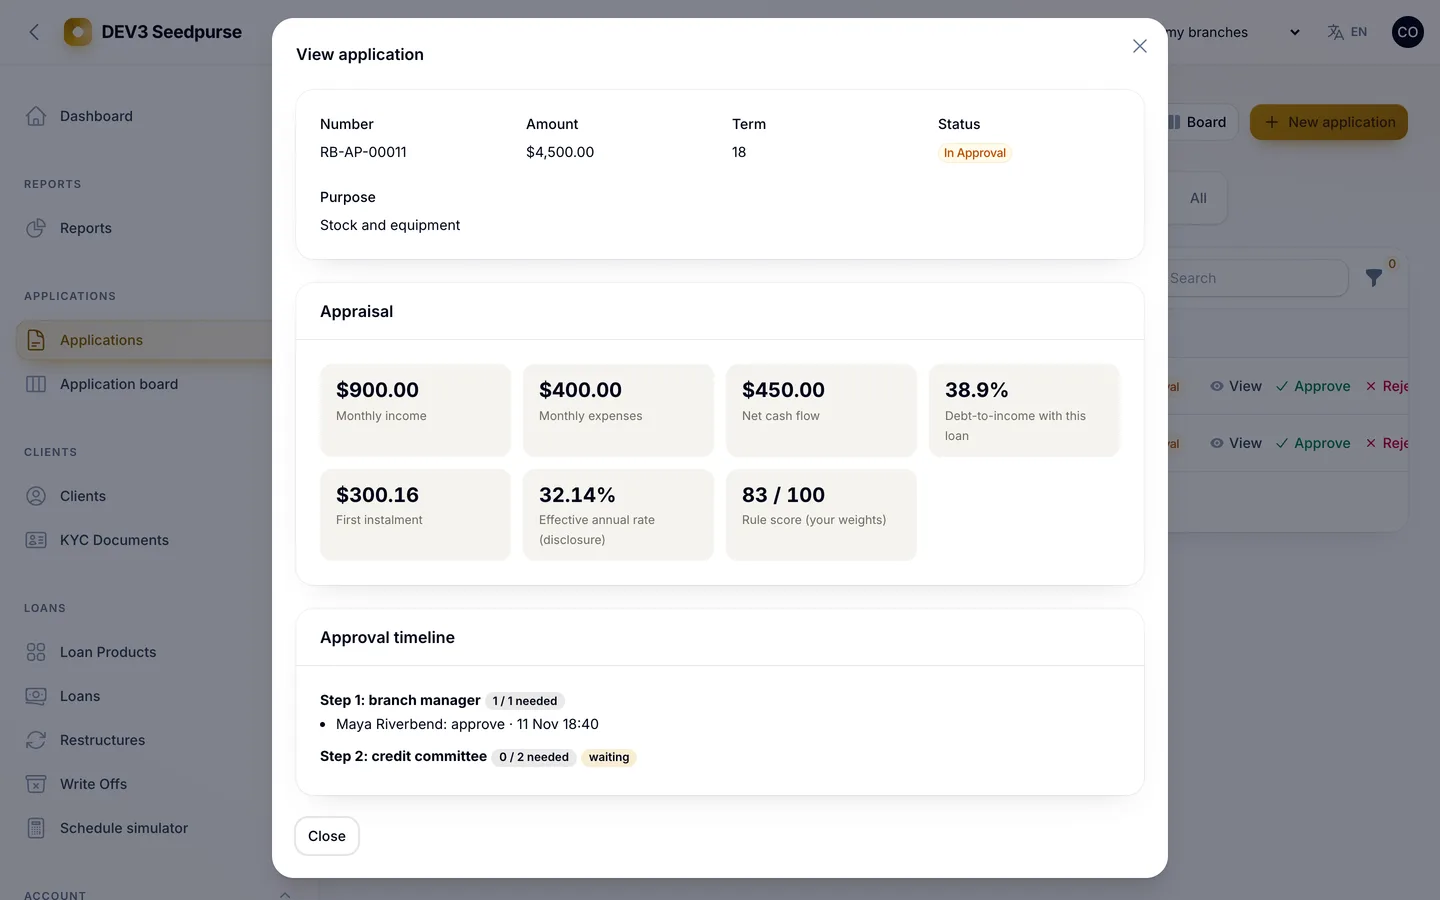
3. Do payments land where your policy says?
A receipt should clear penalties, fees, interest and principal in your order, and a backdated or reversed receipt should replay cleanly. Ask to see where each payment went.
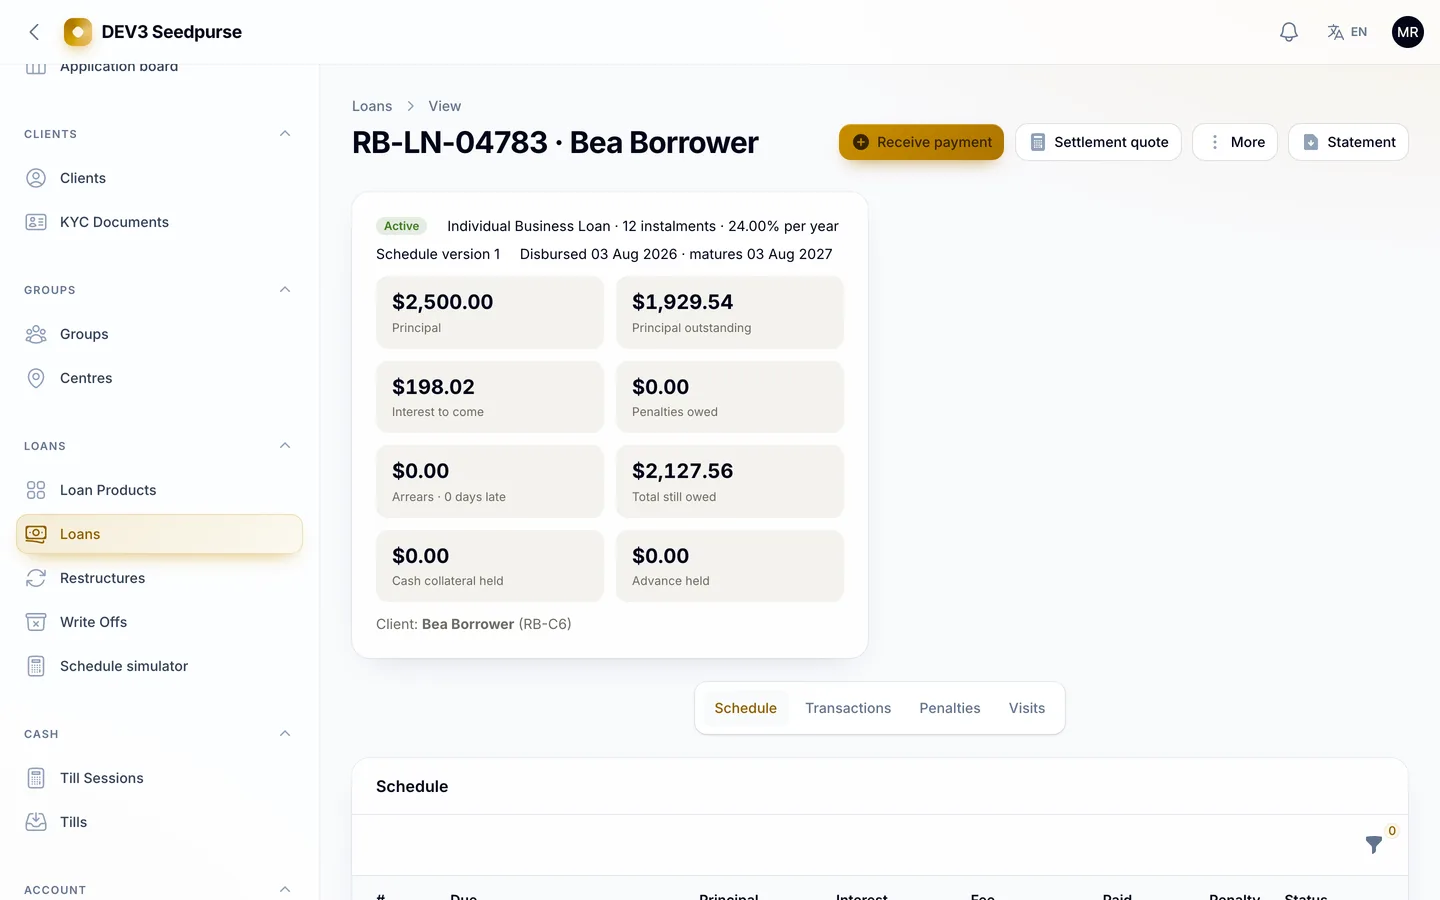
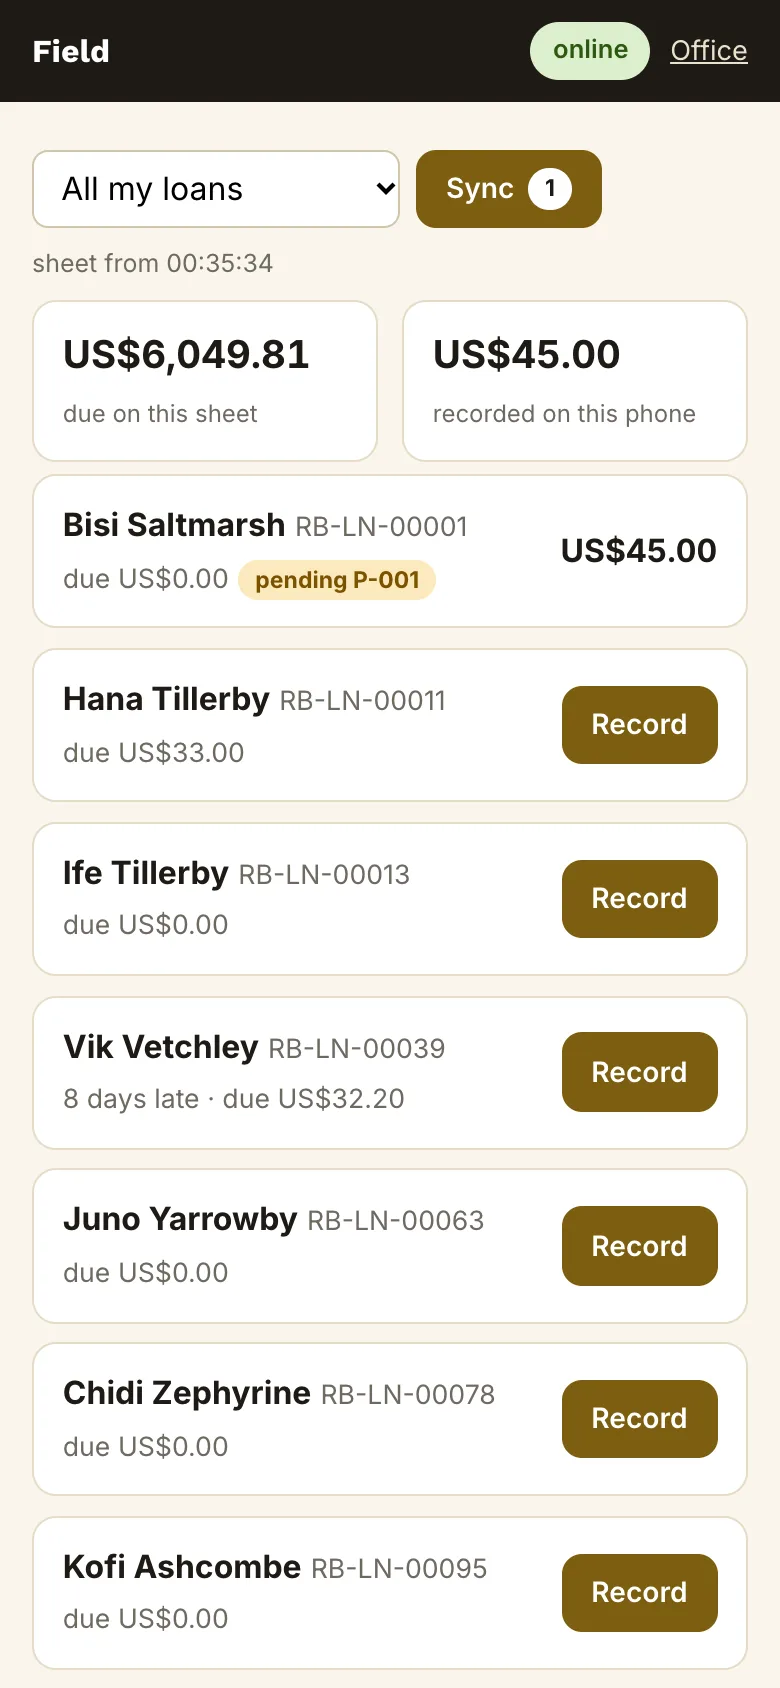
4. Can officers collect in the field without a signal?
The centre meeting happens where coverage is poor. Payments should queue on the phone and sync once, without double receipts.
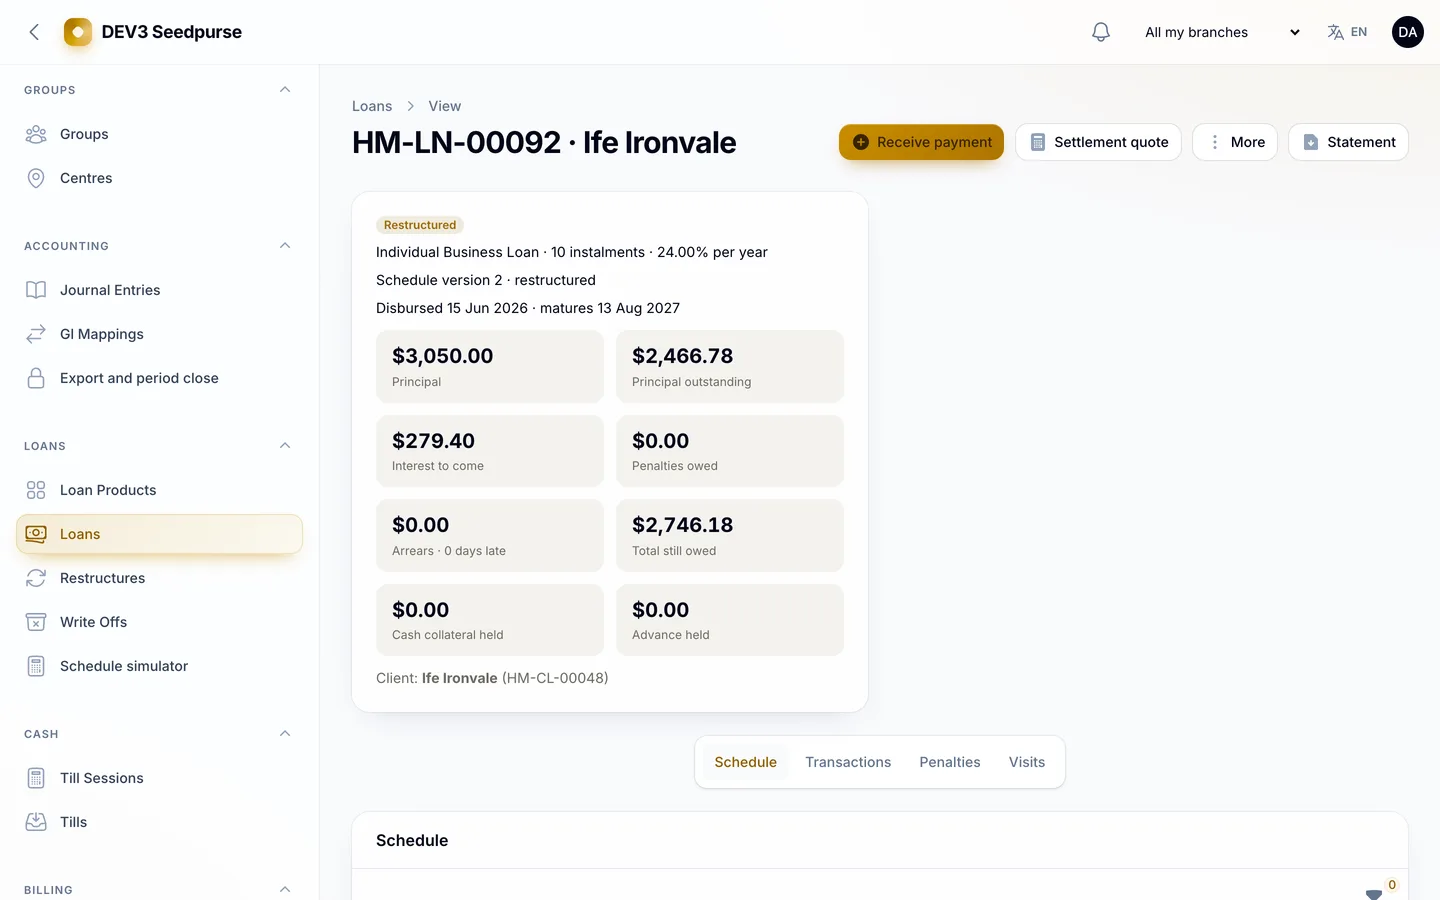
5. Can you restructure, settle and write off with a trail?
Look for new schedule versions that keep the old one, settlement quotes, waivers that need a second signature, and write-offs signed by different people.
6. Are the limits honest?
Seedpurse records disbursements and repayments and moves no money. It takes no deposits, calls no credit bureau and prepares no regulator returns: you export CSV for your own reporting. It serves one lender with branches and is web only.